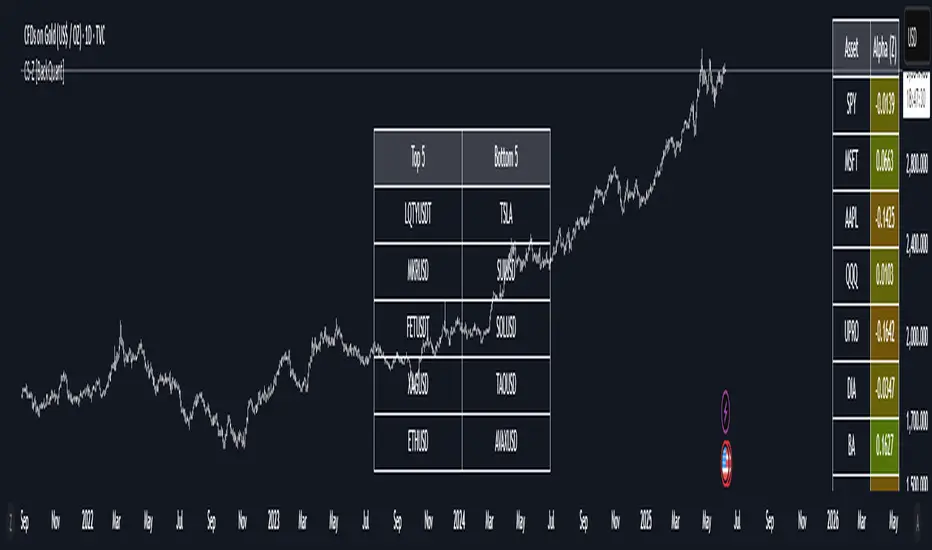
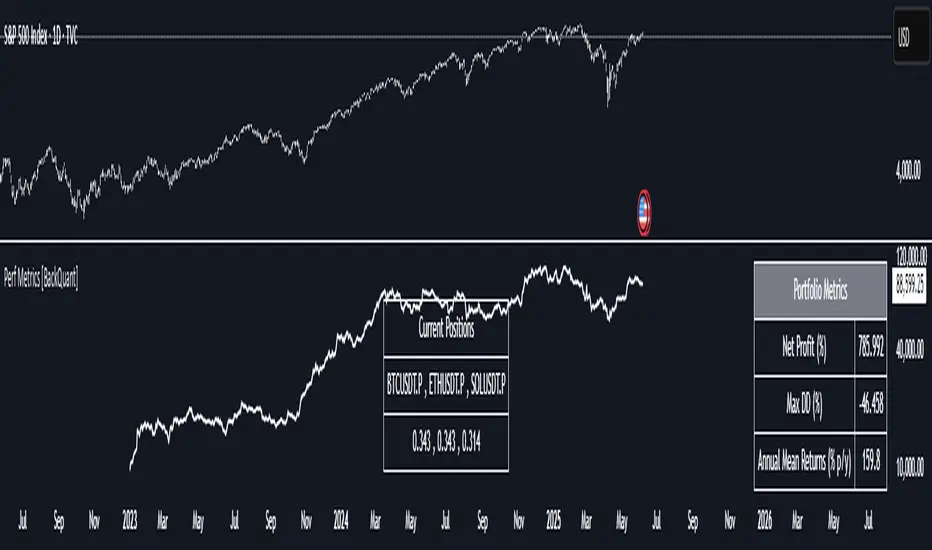
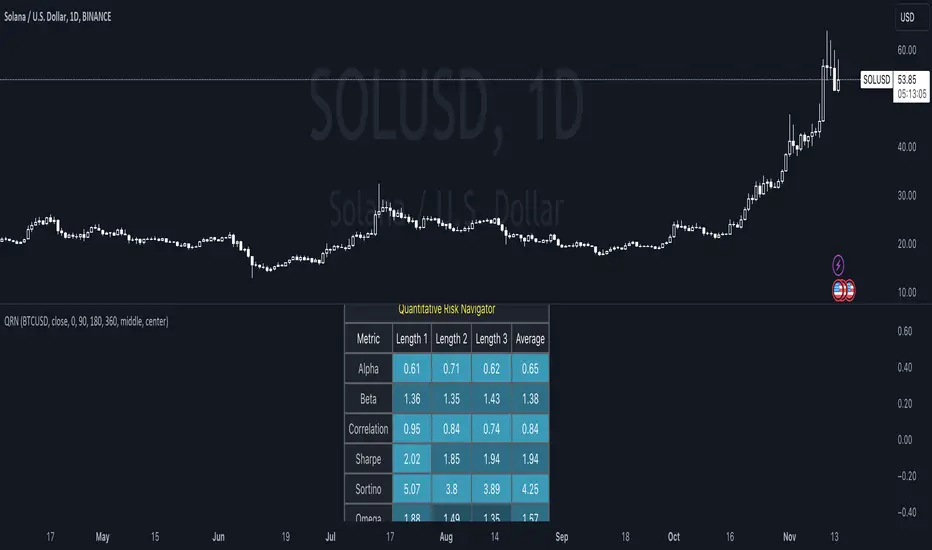
Hourly Alpha Profile Terminal [The Quant Science]Hourly Alpha Profile Terminal is an advanced quantitative analysis tool developed for the TradingView platform, designed for traders operating on intraday timeframes up to 60 minutes. Its main goal is to unveil the hidden structure of price volatility and directionality on an hourly basis , focusing on a specific day of the week chosen by the user. Instead of relying on traditional momentum indicators, this script historically maps market behavior hour by hour, calculating win rates and risk intensity for all 24 hours of the day.
🔷 What It Does
The script performs real-time statistical and visual analysis directly on the chart through two dedicated quantitative terminals.
The Win Rate Profile Terminal divides the entire day into 24 hourly slots from 00:00 to 23:59, analyzes how many hourly cycles closed bullish compared to the total for the selected day of the week, and returns a success percentage win rate and an explicit directional bias of bullish, bearish, or neutral, accompanied by a visual progress bar.
The Volatility Profile Terminal calculates the logarithmically normalized standard deviation of hourly returns for each time slot, generating a volatility index and risk-based intensity bars to identify precisely which hour of the day experiences the most violent price movements as the peak risk slot.
🔷 How to Use It
To obtain correct data, the indicator requires an intraday timeframe less than or equal to 60 minutes, such as 1m, 5m, 15m, or 60m. If applied to daily, weekly, or higher charts, the terminal blocks execution and displays an error warning.
Add the script to your intraday chart on TradingView, open the indicator settings to select the day of the week you want to analyze, and observe the overlapping tables on the chart to identify hours with high win rates above 55% for trend opportunities or hours with extreme volatility for risk management.
🔷 What It Is Used For
Hourly Seasonality Analysis for discovering during which times of day a given asset historically shows a strong directional tendency.
Entry Timing Optimization for avoiding false breakouts during low-directionality or erratic risk hours and focusing on statistical high-probability slots.
Risk Management and Volatility Mapping for understanding when the market becomes more volatile to prevent excessive slippage or correctly position stop losses based on peak risk hours.
🔷 Who Uses It
Day Traders and Scalpers who need a statistical edge based on recurring market behaviors during trading sessions like the London or New York opens.
Quantitative and Systematic Traders looking to filter operational setups by integrating hourly probability matrices.
Market Analysts seeking an objective and visual reading of market microstructure without cluttering the chart with classic oscillators.
🔷 User Interface Management
Settings: Day to Analyze allows you to choose the day of the week to analyze from Monday to Sunday.
Win Rate Terminal Positio n allows you to position the probability table in your preferred corner of the screen using options like Top Right, Top Left, Bottom Right, Bottom Left, or Center.
Win Rate Terminal Size lets you adjust the text size inside the table to Small, Normal, or Large.
Volatility Terminal Position manages the screen position of the volatility table.
Volatility Terminal Size modifies the text size of the volatility table to fit any screen resolution.
🔷 To be used in combination with the Bias Detector Terminal
This script completes a suite consisting of two scripts:
🔹 Bias Detector Terminal used to find a day with a bias. For example, by analyzing Bitcoin on a Daily timeframe, we find a bias for Saturday.
👉 Bias Detector Terminal:
🔹 Hourly Alpha Profile Terminal let us dive deeper into the market and analyze the Saturday intraday session.
インジケーター

Alpha S/R Channel StrategyAlpha S/R Channel Strategy (ASRC)
Mean-reversion strategy trading pullbacks to a dynamic Higher Timeframe EMA channel. Confirms exhaustion via Engulfing & Pin Bar patterns, with Pin+Engulf combo overriding trend filters to capture institutional liquidity grabs. Features optional RSI, BB width, and inverted Squeeze Momentum filters. Includes adaptive position sizing, partial TP, breakeven stops, session trade limits, no-trade windows, day/weekend close, and Friday trading control.
📌 Strategy Overview
Alpha S/R Channel Strategy is a dual‑timeframe mean‑reversion strategy that identifies high‑probability reversal setups by combining a dynamic channel derived from a Higher Timeframe EMA with high‑conviction candlestick patterns (Engulfing and Pin Bar).
The strategy waits for price to retrace to a dynamic value area (the channel) and confirms exhaustion through candlestick patterns before entering—capturing pullbacks within the prevailing trend while avoiding counter‑trend trades.
🧠 Unique Edge – Why This Mashup Works
Most trend‑following strategies chase breakouts and get caught in false moves. Most engulfing strategies ignore the bigger picture and enter too early. This strategy solves both problems by combining these components in a specific sequence:
1. Dynamic EMA Channel (The Value Area)
Instead of using static support/resistance, the strategy constructs a dynamic channel around a Higher Timeframe EMA. The channel width adapts to volatility using three modes:
- Percentage – width as % of current price.(price * (channelWidthPct / 100) )
- ATR Multiplier – width based on ATR from the Higher Timeframe.
- Fixed – static price distance.
Why this matters: The HTF EMA represents the "fair value" or equilibrium price. When price pulls back to this zone, it's statistically more likely to resume the trend rather than reverse.
-------------------------------------------------------------------
2. Channel Break + Candlestick Confirmation (The Trigger)
The strategy enters only when price returns to the channel AND shows exhaustion:
- Bullish Engulfing – Current green candle engulfs previous red/small green candle
- Bearish Engulfing – Current red candle engulfs previous green/small red candle
- Pin Bar + Engulfing Combo – Pin bar sweeps recent high/low and is followed by an engulfing pattern
Why this matters: The channel provides the context (where price should reverse). The candlestick patterns provide the confirmation (that reversal is actually happening). Using both drastically reduces false signals.
-------------------------------------------------------------------
3. Optional Multi‑Layer Filters (The Quality Control)
The strategy includes configurable filters that can be enabled/disabled:
1- EMA Lower TF – Ensures micro‑trend alignment (longs above EMA, shorts below)
However, there is a critical override:
🔄 Pin Bar + Engulfing Combo OVERRIDES the EMA Confirmation
When a Pin Bar sweeps the N‑bar high/low (proving a breakout attempt failed) and is immediately followed by an Engulfing pattern on the next candle, this combo represents a "double confirmation" of exhaustion that bypasses the EMA filter.
Why this is a breakthrough:
Strong institutional reversals (liquidity grabs) often happen against the short‑term EMA trend. A pure trend‑following strategy with a strict EMA filter would miss these reversals because price is moving against the EMA.
2- Higher Timeframe EMA – Ensures long‑term trend alignment
This acts as a "trend filter on top of the trend filter" – preventing entries that go against the even larger market structure. Users can select a separate timeframe (e.g., 1H) with its own EMA length for additional confirmation.
3- RSI – Prevents buying above 70 and selling below 30
4- Bollinger Bands – Blocks entries during low volatility (sideways markets)
5- Squeeze Momentum – This strategy uses an inverted Squeeze Momentum logic:
"val < 0 → Longs allowed, Shorts blocked"
"val > 0 → Shorts allowed, Longs blocked"
"val == 0 → Both allowed"
This inversion is intentional. The strategy is mean‑reversion based—it waits for momentum to become overextended and then trades against that momentum
These filters are optional because different assets and market conditions require different levels of confirmation. The user has full control.
-------------------------------------------------------------------
4. Comprehensive Risk Management
The strategy includes:
- Position Sizing – Fixed percentage of equity per trade (separate for first and second entry)
- Pyramiding – Allows up to 2 positions in the same direction (second trade uses lower risk)
- Multiple SL Options – Low-High, Swing high/low, Channel, Fixed distance
- Trade Counter Reset – Resets at session starts for scalping timeframes, daily for swing
- No‑Trade Windows – Blocks entries during end‑of‑day volatility (active only for TF ≤ 15m)
- Day/Week End Closing – Closes positions before gaps (configurable by timeframe)
- Partial Take Profit – Closes a configurable percentage (default: 50%) at a specified R:R ratio (default: 1:2), allowing the remainder to run to the full target (default: 1:3)
- Breakeven Stop – Optionally moves the stop loss to breakeven when the first TP level is reached, protecting the remaining position from turning into a loss
Why this matters: The risk controls ensure survivability across different market conditions. Also Breakeven protection reduces the risk of winning trades turning into losers.
-------------------------------------------------------------------
📊 How It Works
1. Dynamic Channel Calculation
The strategy constructs a channel around an Exponential Moving Average (EMA) from a selected Higher Timeframe:
- EMA – Calculated on the Higher Timeframe
- Channel Width – Adaptive based on volatility (Percentage, ATR, or Fixed)
- Upper Band = EMA + (Width / 2)
- Lower Band = EMA - (Width / 2)
Channel Width Modes:
- Percentage – Width = Price × (User‑defined %)
- ATR Multiplier – Width = ATR(14) × Multiplier
- Fixed – Width = Static distance
-------------------------------------------------------------------
2. Entry Signal Detection
Trades are executed on the Lower Timeframe (default: 5m) when all conditions are met:
Pattern Requirements (One of the following):
- Bullish Engulfing: Current green candle completely engulfs previous bearish or small green candle
- Bearish Engulfing: Current red candle completely engulfs previous bullish or small red candle
- Pin Bar + Engulfing Combo: Pin bar sweeps recent high/low AND is followed by engulfing pattern (Overrides LTF EMA)
# Engulfing Filters:
Body Only – Only bodies must engulf (not full range)
Min/Max Range – Configurable via Percentage, ATR, or Fixed
Gap Allowance – Controls how much gap is allowed in the wrong direction
Previous Range % – Limits the size of the prior candle when it's in the same color
# Pin Bar Detection:
- Wick/Body Ratio (default: 3.0) – Wick must be 3× larger than body
- Max Body/Range (default: 0.20) – Body must be ≤20% of total range
- Min Wick/Range (default: 0.70) – Wick must be ≥70% of total range
- Sweep Lookback (default: 10 bars) – Pin bar must sweep a recent high/low
Min Pin Bar Range % – Pin bar must meet a minimum size threshold
# Channel Proximity:
Price must be within the channel boundaries (open inside)
-------------------------------------------------------------------
3. Confirmation Filters (All Optional)
- Lower Timeframe EMA : Longs require price > EMA; Shorts require price < EMA (overridden by Pin+Engulf combo)
- Higher Timeframe EMA : Ensures long‑term trend alignment (longs above HTF EMA, shorts below)
- RSI : Prevents longs above 70; Prevents shorts below 30
- Bollinger Bands : Blocks entries when BB width < threshold (low volatility)
- Squeeze Momentum : Ensures momentum matches trade direction (inverted logic)
-------------------------------------------------------------------
4. Risk & Position Management
# Position Sizing:
- First Trade – Fixed % of equity (default: 2%)
- Second Trade – Separate % of equity (default: 1%)
- Position size = (Account Risk) / (Entry – SL Distance)
# Friday Trading:
- Allow Friday Trading (default: Disabled) – When disabled, no new trades will be opened on Fridays. Existing positions are not affected. This helps avoid weekend gap risk as markets close for the week.
# Stop‑Loss Options:
1- Low-High : Entry bar low/high ± buffer
2- Swing high/low : N-bar low/high ± buffer
3- Channel : Channel band ± buffer
4- Fixed distance : Fixed price distance from entry
# Take Profit:
- Main R:R ratio (default: 1:3)
- Separate R:R for second trade (default: 1:3)
# Trade Counter Reset:
TF ≤ 15m – Resets at Asia (20:00 NY), London (03:30 NY), New York (09:30 NY)
TF > 15m – Resets once per day at session start
# No‑Trade Window:
- Active only for TF ≤ 15m (16:45–19:05 NY time)
- Protects against end‑of‑day volatility spikes
# Close All Positions:
- TF ≤ 15m – Can close at day end and/or week end (configurable)
- 15m < TF ≤ 240m – Week end only
- TF > 240m – Feature disabled
# Entry Spacing:
- Minimum Bars Between Entries (default: 4) – Prevents multiple entries on the same bar or too close together, reducing the impact of whipsaw on tightly clustered signals
⚙️ Default Settings – Optimized for XAUUSD (Gold)
All default values have been specifically calibrated for Gold's typical volatility and intraday structure.
Setting \ Default \ Why This Works for Gold
-----------------------------------------------------------------------------------
Higher Timeframe \ 15m \ Gold's intraday rhythm operates on 15‑minute cycles. This timeframe captures the balance between institutional order flow and retail noise.
-----------------------------------------------------------------------------------
EMA Length \ 36 \ approximately one full trading session. This captures the dominant intraday trend without excessive lag.
-----------------------------------------------------------------------------------
Channel Width Mode \ Percentage \ Gold's price levels change over time. Percentage mode ensures the channel scales with price, maintaining consistent relative width regardless of Gold's price level.
-----------------------------------------------------------------------------------
Channel Width \ 0.35% \ Gold's daily range averages $30–$100. At current prices, 0.35% = approximately $113–$16. This width captures ~70% of Gold's daily volatility, creating a meaningful "value zone" that filters noise while remaining relevant.
-----------------------------------------------------------------------------------
Lower Timeframe \ 5m \ Fast enough to capture entry signals within the same session, slow enough to filter out micro‑noise. 5m is Gold's "sweet spot" for intraday entries.
-----------------------------------------------------------------------------------
Engulfing Mode \ Percentage \ Adapts to Gold's volatility. As Gold's price moves, the required engulfing range scales proportionally—ensuring consistent pattern quality.
-----------------------------------------------------------------------------------
Engulfing Min Range \ 0.098% \ At Gold's current price3000-5000, this ≈ $3.0–$5.0. Anything smaller is just market noise, not a meaningful reversal signal.
-----------------------------------------------------------------------------------
Engulfing Max Range \ 0.550% \ At Gold's current price, this ≈ $20–$25. Larger candles are often blow‑off spikes driven by news —they tend to reverse violently, making them poor entry points.
-----------------------------------------------------------------------------------
Previous Range % \ 0.60 \ Allows the prior candle to be up to 60% of the engulfing candle's range. This is Gold's "consolidation before reversal" pattern—a small same‑color candle before a large reversal candle.
-----------------------------------------------------------------------------------
Gap Allowance \ 250 ticks \ Gold's typical spread and gap behavior. (250 ticks = $0.250 However, tick values vary between brokers), which accommodates normal gaps without allowing extreme invalid gaps.
-----------------------------------------------------------------------------------
Pin Bar Sweep \ 10 bars \ On a 5m chart, 10 bars = 50 minutes. Gold's liquidity grabs often occur within a 30–60 minute window. 10 bars captures these recent liquidity zones without looking too far back.
-----------------------------------------------------------------------------------
Pin Bar Range % \ 0.70 \ Requires the pin bar(high-low) to be at least 70% of the minimum engulfing range. This ensures the pin bar has enough size to be meaningful—rejecting tiny pin bars that lack conviction.
-----------------------------------------------------------------------------------
Risk per Trade (1st) \ 2% \ Gold experiences 3–5 trade losing streaks regularly. 2% risk ensures that a typical losing streak results in only 6–10% drawdown—recoverable with a few winning trades.
-----------------------------------------------------------------------------------
Risk per Trade (2nd) \ 1% \ When pyramiding, total exposure increases. 1% on the second trade limits worst‑case loss to -3% total (2% + 1%), protecting the account during false reversals.
-----------------------------------------------------------------------------------
Risk:Reward \ 1:3 \ Gold routinely moves 1.5–2× its ATR in a single directional push. A 1:3 target (e.g., $15 on a $5 stop) is well within Gold's typical daily range—achievable without being overly ambitious.
-----------------------------------------------------------------------------------
Stop‑Loss Reference \ Channel \ Aligns the stop with the value area. If price breaks beyond the channel, the mean‑reversion thesis is invalidated. This is the most logical stop placement for this strategy.
-----------------------------------------------------------------------------------
Stop‑Loss Buffer \ 500 ticks \ 500 ticks = ($0.50 ) on Gold. However, tick values vary between brokers so The table on chart will display and show the calculated dollar value. This provides a safety buffer against spread, slippage, and normal wicks—preventing premature stops while keeping the stop within the value area.
-----------------------------------------------------------------------------------
Partial TP & Breakeven \ Disabled (50%, 1:2) \ Optional features that allow locking in partial profits and protecting positions once they move in your favor. Recommended to enable after forward testing.
-----------------------------------------------------------------------------------
No‑Trade Window \ Enabled \ 16:45–19:05 NY time captures the end‑of‑day volatility spike. Gold often experiences erratic moves during this period as institutional traders close positions.
-----------------------------------------------------------------------------------
Day End Close \ Enabled \ Gold gaps frequently at the daily open (5:00 PM NY). Closing before day end avoids these gaps, which can easily stop out tight positions.
-----------------------------------------------------------------------------------
Week End Close \ Enabled \ Gold is highly sensitive to weekend news (geopolitics, central banks). Gaps of $20–$50+ are common at Sunday open. Closing before Friday close is essential.
-----------------------------------------------------------------------------------
EMA Lower TF \ Enabled \ Ensures entries align with the 5m micro‑trend. However, the Pin+Engulf combo overrides this filter to capture institutional reversals against the trend.
-----------------------------------------------------------------------------------
Higher TF EMA \ Enabled (1H, 55) \ Provides an additional layer of trend confirmation at the macro level. The 1H 55‑EMA acts as a reliable gauge of the broader intraday trend, preventing entries against strong momentum.
-----------------------------------------------------------------------------------
RSI \ Enabled length(14) \ Prevents buying when Gold is overbought (RSI > 70) and selling when oversold (RSI < 30). Gold's sharp spikes often create extreme RSI readings—this filter avoids chasing exhausted moves.
-----------------------------------------------------------------------------------
Bollinger Bands \ Enabled \ locks entries during low volatility (BB width < 0.002). Gold sometimes enters tight consolidation ranges (BB width < 0.002) where engulfing patterns fail. This filter avoids trading in these conditions.
-----------------------------------------------------------------------------------
Squeeze Momentum \ Enabled \ This is inverted from standard SQZMOM. Gold's momentum often overshoots before reversing. By fading the extreme (longs when val < 0, shorts when val > 0), the strategy captures the reversal rather than chasing the continuation.
-----------------------------------------------------------------------------------
# Important Notes on Backtest Realism
- Commission – Most ECN/raw-spread brokers charge $3.00–$3.50 per side (round-turn commission of $6.00- $7.00) for 1 standard lot (100 oz) of XAUUSD. Standard accounts usually build the fee into a wider spread instead of charging a separate cash. This strategy deducts $3.50 per entry and $3.50 per exit ($0.035 × 100 oz)round-turn commission of $7.00. Adjust this to match your broker's exact fees.
- 4 ticks Slippage – For XAUUSD on OANDA, 1 tick = $0.001** per ounce (3 decimal places). 4 ticks = **$0.004 per ounce. Adjust this value if your broker quotes XAUUSD with different decimal precision (e.g., 2 decimal = $0.01 per tick).
Always adjust the commission value to your broker's exact fee structure before relying on the results.
"A backtest without realistic commission and slippage is a fantasy. A backtest with realistic commission and slippage is a truthful reflection of what you can expect when trading live."
-------------------------------------------------------------------
📊 Chart Display
Channel – Upper/Lower bands with a semi‑transparent fill (red zone), representing the value area
EMA Lower TF – Green EMA on the lower timeframe for confirmation
HTF EMA Filter – Red EMA line showing the additional trend filter (plotted on all timeframes ≤ its TF)
Info Table – Shows Market Status, EMA confirmations, Channel Width, Engulfing ranges, SL settings,
Filters, No‑Trade Window status, Session Close status
Signal Arrows – Green arrow pointing up (below bar) for Long entries, Red arrow pointing down (above bar) for Short entries
Historical Trades – Configurable number of past trades to display on the chart (default: 111, max: 125). Adjust this to optimize chart performance while keeping sufficient trade history for visual analysis.
Reset Signal – Arrow marker (grey) indicating when the trade counter resets at session starts (Asia, London, New York for TF ≤ 15m, or daily for larger TFs)
Background Colors – red for No‑Trade Window, Gray/White for Session Close
UI Note
# When you adjust any setting in the Inputs tab (Channel Width, Engulfing Min/Max, Previous Range, SL Buffer, etc.), the values displayed in the info table update automatically in real‑time.
This allows you to:
- See the impact of your changes immediately
- Verify the actual dollar values of your settings at current price levels
- Fine‑tune parameters without switching between tabs
Example: If you change the Channel Width from 0.35% to 0.50%, the info table will instantly show the new width in dollars (e.g., $8.50 → $12.00).
# Inputs are hidden from the status line to keep the chart clean. All settings (zones, EMAs, risk, patterns) remain fully adjustable in Settings → Inputs tab.
-------------------------------------------------------------------
📌 In Summary:
This is not a random collection of indicators.
- The HTF EMA Channel provides the structural context – a dynamic value area that adapts to volatility.
- The Engulfing/Pin Bar patterns provide the high‑conviction trigger – exhaustion confirmation.
- The EMA Override provides the institutional edge – capturing liquidity grabs that standard EMA‑based strategies miss.
- The Optional Filters provide the quality control – reducing false signals.
- The Risk Management provides the survivability – realistic position sizing and stops.
Each component exists specifically to compensate for a flaw in the others. This interdependency is what makes the strategy original, robust,
Author: Awab_Hassan
ストラテジー

Master Portfolio Lab PRO [The Quant Science]The Master Portfolio Lab PRO is an advanced quantitative analysis terminal designed to transform TradingView into a powerful multi-asset portfolio management engine. Developed with institutional-grade calculation logic, this tool allows you to simulate, monitor, and analyze the combined performance of 12 customizable assets within a single, dynamic environment.
In a world where trading is often hyper-focused on a single ticker, the Master Lab enables you to level up: stop looking at the tree and start managing the forest.
🧪 USAGE
The script is designed for traders and investors looking to validate asset allocation strategies or monitor their real-market exposure against a specific benchmark.
🧬 How to configure it:
Asset Allocation: Enter your desired tickers (Crypto, Stocks, Forex, or Commodities) and assign a percentage weight to each slot. Ensure the total weight equals 100%.
Capital Configuration: Choose from predefined capital profiles (from $1k to $1M) or set a custom capital amount for precise simulations.
Costs & Fees: Set a "Portfolio Fee" to reflect transaction costs and generate a realistic, non-theoretical equity curve.
Benchmark Comparison: Select a reference index (e.g., S&P 500 or Bitcoin) to measure the Alpha generated by your active management.
🧪 DETAILS
🧬 Multi-Mode Analysis Engine
The script offers four independent visualization modes, instantly switchable via the settings menu:
Cumulative (%): Comparative analysis between the portfolio's percentage return and the benchmark.
Equity ($): Monetary monitoring of net liquidity and cash growth.
SMA Ribbon: Identification of the portfolio's trend regime using moving averages applied directly to the equity curve.
Volatility: Real-time monitoring of portfolio "thermal stress" via smoothed Standard Deviation (WMA).
🧬 Alpha-Glow Logic
The system utilizes a high-fidelity visual architecture based on dynamic gradients. When the portfolio outperforms the benchmark (Positive Alpha), the fill area illuminates, providing immediate psychological feedback on the quality of your management.
🧬 Real-Time Dashboard
An integrated table in the bottom-right corner processes live data to provide:
Net Value: Current portfolio value, including PnL and costs.
Return %: Total return from the selected starting anchor point.
Alpha vs Index: The "holy grail" of trading—exactly how much value you are adding compared to a passive investment.
🧪 SETTINGS
🧬 Capital Configuration
1) Fixed Capital: Toggle quick selectors for standard account sizes.
2) Custom Capital: Manual input for simulating specific real-world accounts.
🧬 Date Period Analysis
Allows you to set a precise start date (Day/Month/Year) to analyze portfolio performance during specific macroeconomic events or historical cycles.
The Master Portfolio Lab PRO was born from the need to overcome TradingView's native limitations in multi-symbol management. By utilizing normalization techniques and iterative Rate of Change (ROC) calculations, we have created a framework capable of simulating an entire investment fund with surgical precision. インジケーター

Institutional Alpha Vector | D_QUANT Institutional Alpha Vector | D_QUANT
Overview
The Institutional Alpha Vector (IAV) is an original trend-following framework that replaces single-indicator bias with a Weighted Composite Score . Instead of relying on a simple moving average, this script aggregates four distinct quantitative dimensions—Price, Momentum, Volatility, and Volume—into a normalized value called the "Alpha Vector."
The goal of this tool is to identify "Institutional Consensus"—periods where multiple mathematical models align in the same direction, reducing the likelihood of false breakouts in choppy markets.
How It Works: The Quantitative Engines
The script calculates four independent signals. For each module, a state is stored (1 for Bullish, -1 for Bearish, 0 for Neutral).
1. Price Filter (Hull Moving Average):
The script uses an HMA (a weighted moving average that reduces lag by using the square root of the period). A signal is triggered when the price crosses over/under this "Spine."
2. Volatility Regime (RMA + ATR):
This module uses a Moving Average (RMA) combined with an Average True Range (ATR) offset. It acts as a volatility filter that price must move beyond 1 ATR from the mean to register a trend, ensuring the market isn't just "drifting."
3. Momentum Physics (ADX/DMI):
Based on J. Welles Wilder’s Directional Movement Index. It checks if the is above (or vice versa) but only if the ADX (Average Directional Index) is above a user-defined threshold (default: 10), confirming the presence of a strong trend.
4. Institutional Flow (Chaikin Money Flow):
This confirms price action with volume. It calculates the accumulation/distribution of money flow over a specific period. A signal is only valid if the CMF is positive (Bullish) or negative (Bearish).
The Alpha Vector Calculation
This is the core "originality" of the script. The indicator takes the active modules and calculates a Composite Score :
This results in a value between -1.0 and +1.0 .
* High Confidence Long: When the score exceeds +0.1 (adjustable).
* High Confidence Short: When the score drops below -0.1 (adjustable).
* Neutral Zone: When the score is near 0, the script colors the bars grey, signaling a lack of institutional consensus.
Visual Intelligence: The "Electric Conduit"
The script visualizes market energy through a custom rendering engine:
* The Spine: A central line representing the HMA trend.
* The Conduit (Fill): A dynamic gradient that expands or contracts based on the ATR (Average True Range) . This allows traders to see "volatility expansion" (wide ribbon) vs "compression" (tight ribbon) at a glance.
* Bar Coloring : Automatically aligns the chart candles with the Alpha Vector state to remove cognitive load.
How to Use
1. Define your Strategy: In the settings, you can toggle specific modules. If you are trading a low-volume asset, you might disable the **CMF** module.
2. Identify the Consensus: Look for the ribbon to change from Grey (Neutral) to Cyan/Gold.
3. Monitor the HUD: A small dashboard in the bottom right displays the live Alpha Vector score. A score of 1.0 means all four engines are in 100% bullish agreement.
Disclaimer: Trading involves significant risk. This tool is for educational and analytical purposes and does not constitute financial advice. インジケーター

Quant Stats: Alpha, Beta, R2Quant Stats Indicator for TradingView: Alpha, Beta, and R-Squared
Overview
The Quant Stats Indicator is a professional-grade Pine Script tool designed for quantitative traders and hedge fund managers who need real-time analysis of stock or ETF performance against a benchmark using three fundamental CAPM metrics: Beta, R-Squared, and Alpha.
This indicator calculates three critical measurements that answer every quant trader's core questions: How volatile is this asset relative to my benchmark? How much of its performance is independent of the benchmark? And how much excess return am I achieving after adjusting for risk?
The Three Metrics Explained
Beta (β) measures systematic risk and volatility relative to your chosen benchmark. A Beta of 1.0 means the asset moves in lockstep with the benchmark. A Beta above 1.0 indicates higher volatility—if the market rises 10%, a Beta-1.5 asset should rise 15%. Conversely, a Beta below 1.0 indicates lower volatility, making it a defensive position. This metric helps you understand how much market exposure you're truly taking.
R-Squared (R²) quantifies what percentage of an asset's price movement can be explained by benchmark movements. An R² of 0.95 means 95% of the asset's moves are driven by the benchmark, leaving only 5% unexplained. Conversely, an R² of 0.2 means 80% of the asset's movement is independent of the benchmark. This distinction is crucial: high R² is desirable for passive index tracking but indicates weak alpha potential; low R² reveals genuine independent returns, exactly what active managers seek.
Alpha (α) reveals Jensen's Alpha—the excess risk-adjusted return after accounting for the return you "should" earn given your Beta exposure. A positive Alpha of 15% means you're outperforming the market by 15 percentage points after adjusting for systematic risk. This is the holy grail of stock picking: pure skill-driven excess return, not luck from market exposure.
How to Use It
Configure four key inputs: your benchmark ticker (default SPY, but use QQQ for tech-focused analysis or sector-specific ETFs), the lookback period in days, and the risk-free rate reflecting current Treasury yields. The lookback period is critical. Use 20 days for tactical trading to capture short-term sentiment and beta spikes; use 63 days for swing trading and quarterly rebalancing; use 252 days for structural asset allocation decisions.
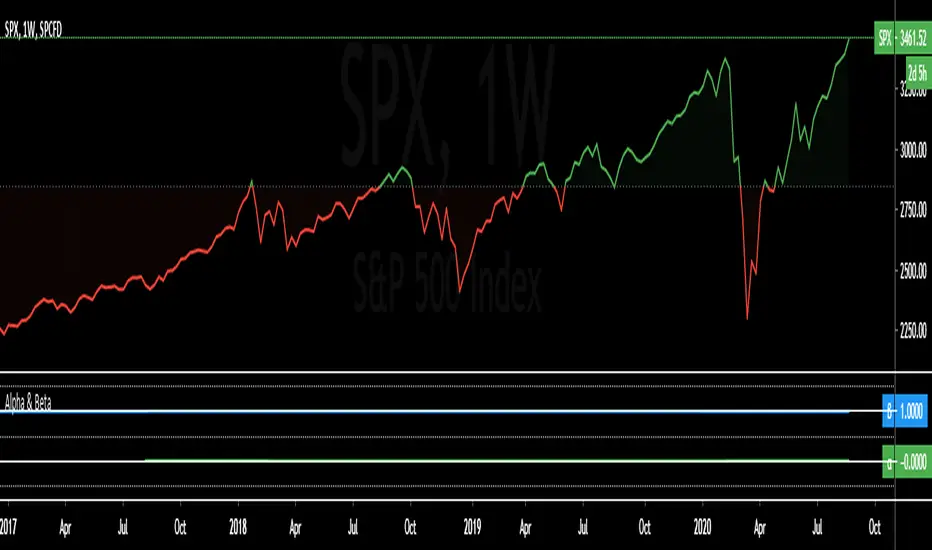
The indicator plots Beta as a blue line, R-Squared as a red shaded background area, and Alpha as a green line in a sub-panel. Reference gridlines appear at Beta = 1.0 (market-equivalent volatility) and Alpha = 0.0 (breakeven performance), making interpretation intuitive.
Practical Applications
For swing traders monitoring a 63-day window, seek positions with low Beta (below 0.8) and positive Alpha—these are defensive winners. Avoid high Beta (above 1.2) with low R² unless you specifically want high-volatility speculation. Long/short hedge funds should use a 20-day lookback to detect regime changes: sudden Beta spikes often precede correlation breakdowns, while R² collapses signal rising idiosyncratic risk requiring immediate rebalancing.
For ETF portfolio construction, high R² (above 0.95) indicates index-tracking that doesn't justify active management fees. Low R² (below 0.3) combined with positive Alpha reveals genuine active management skill. The sweet spot is moderate Beta (0.5–0.8) with low R² and positive Alpha—a true diversifier that reduces portfolio volatility while generating independent returns.
Critical Interpretation Rules
A common mistake is assuming high R² is always desirable. It isn't. Passive index funds naturally have high R²; active managers should target low R² with high Alpha. Similarly, don't assume Alpha above 10% is sustainable—short-term Alpha (20–100 days) is inherently volatile and often represents temporary mispricings rather than repeatable skill. Always pair Beta analysis with R² interpretation; Beta alone ignores idiosyncratic risk, liquidity constraints, and tail risk.
Configuration Recommendations
Conservative investors should use SPY as benchmark with a 252-day lookback, targeting Alpha above 3% and Beta below 0.8. Growth-oriented portfolios might use QQQ with a 63-day lookback, targeting 8–12% Alpha and tolerating Beta up to 1.3. Hedge funds pursuing market-neutral strategies should use SPY with a 20-day lookback, set the risk-free rate to 2% (anticipating rate cuts), and target 15%+ Alpha while maintaining Beta below 0.3.
Important Limitations
The indicator is backward-looking; historical statistical relationships may not persist. Shorter lookback periods are noisier but more responsive; longer periods smooth noise but lag regime changes. Choosing the wrong benchmark completely invalidates analysis. Finally, the indicator doesn't account for tail risk or extreme market events where correlations spike unpredictably and Beta becomes unreliable.
Use this tool to separate signal from noise and identify true alpha generators. Apply it consistently, validate results against official fund factsheets, and monitor for 2–4 weeks before making significant portfolio decisions. インジケーター

Infinite EMA with Alpha Control♾️ Infinite EMA with Alpha Control
What Makes This EMA "Infinite"?
Unlike traditional EMA indicators that are limited to typical periods (1-5000), this Infinite EMA breaks all boundaries. You can create EMAs with periods of 1,000, 10,000, or even 1,000,000 bars - that's why it's called "infinite"! Also Infinite EMA starts working immediately from the very first bar on your chart
Why This EMA is "Infinite":
1. Mathematically: When N → ∞, alpha → 0, meaning infinitely long "memory"
2. Practically: You can set any period - even 100,000 bars
3. Flexibility: Alpha allows precise control over the "forgetting speed"
How Does It Work?
The magic lies in the Alpha parameter. While regular EMAs use fixed formulas, this indicator gives you direct control over the EMA's "memory" through Alpha values:
• High Alpha (0.1-0.2): Fast reaction, short memory
• Medium Alpha (0.01-0.05): Balanced response
• Low Alpha (0.0001-0.001): Extremely slow reaction, very long memory
• Ultra-low Alpha (0.000001): Almost frozen in time
The Mathematical Formula:
Alpha = 2 / (Period + 1)
This means you can achieve any EMA period by adjusting Alpha, giving you infinite flexibility!
Expanded "Infinite EMA" Table:
Period EMA (N) - Alpha (Rounded) - Alpha (Exact) - Description
10 - 0.1818 - 0.181818... - Fast EMA
20 - 0.0952 - 0.095238... - Short-term
50 - 0.0392 - 0.039215... - Medium-term
100 - 0.0198 - 0.019801... - Long-term
200 - 0.0100 - 0.009950... - Standard long-term
500 - 0.0040 - 0.003996... - Very long-term
1,000 - 0.0020 - 0.001998... - Super long-term
2,000 - 0.0010 - 0.000999... - Ultra long-term
5,000 - 0.0004 - 0.000399... - Mega long-term
10,000 - 0.0002 - 0.000199... - Giga long-term
25,000 - 0.00008 - 0.000079... - Century-scale EMA
50,000 - 0.00004 - 0.000039... - Practically motionless
100,000 - 0.00002 - 0.000019... - "Glacial" EMA
500,000 - 0.000004 - 0.000003... - Geological timescale
1,000,000 - 0.000002 - 0.000001... - Approaching constant
5,000,000 - 0.0000004 - 0.0000003... - Virtually static
10,000,000 - 0.0000002 - 0.0000001... - Nearly flat line
100,000,000 - 0.00000002 - 0.00000001... - Mathematical infinity
Formula: Alpha = 2/(N+1) where N is the EMA period
Key Features:
Dual EMA System: Run fast and slow EMAs simultaneously
Crossover Signals: Automatic buy/sell signals with customizable alerts
Alpha Control: Direct mathematical control over EMA behavior
Infinite Periods: From 1 to 100,000,000+ bars
Visual Customization: Colors, fills, backgrounds, signal sizes
Instant Start: Works accurately from the very first bar
Update Intervals: Control calculation frequency for noise reduction
Why Choose Infinite EMA?
1. Unlimited Flexibility: Any period you can imagine
2. Mathematical Precision: Direct alpha control for exact behavior
3. Professional Grade: Suitable for all trading styles
4. Easy to Use: Simple settings with powerful results
5. No Warm-up Period: Accurate values from bar #1
Simple Explanation:
Think of EMA as a "memory system":
• High Alpha = Short memory (forgets quickly, reacts fast)
• Low Alpha = Long memory (remembers everything, moves slowly)
With Infinite EMA, you can set the "memory length" to anything from seconds to centuries!
⚡ Instant Start Feature - EMA from First Bar
Immediate Calculation from Bar #1
Unlike traditional EMA indicators that require a "warm-up period" of N bars before showing accurate values, Infinite EMA starts working immediately from the very first bar on your chart.
How It Works:
Traditional EMA Problem:
• Standard 200-period EMA: Needs 200+ bars to become accurate
• First 200 bars: Shows incorrect/unstable values
• Result: Large portions of historical data are unusable
Infinite EMA Solution:
Bar #1: EMA = Current Price (perfect starting point)
Bar #2: EMA = Alpha × Price + (1-Alpha) × Previous EMA
Bar #3: EMA = Alpha × Price + (1-Alpha) × Previous EMA
...and so on
Key Benefits:
No Warm-up Period: Start trading signals from day one
Full Chart Coverage: Every bar has a valid EMA value
Historical Accuracy: Backtesting works on entire dataset
New Markets: Works perfectly on newly listed assets
Short Datasets: Effective even with limited historical data
Practical Impact:
Scenario Traditional EMA Infinite EMA
New cryptocurrency Unusable for first 200 days ✅ Works from day 1
Limited data (< 200 bars) Inaccurate values ✅ Fully functional
Backtesting Must skip first 200 bars ✅ Test entire history
Real-time trading Wait for stabilization ✅ Trade immediately
Technical Implementation:
if barstate.isfirst
EMA := currentPrice // Perfect initialization
else
EMA := alpha × currentPrice + (1-alpha) × previousEMA
This smart initialization ensures mathematical accuracy from the very first calculation, eliminating the traditional EMA "ramp-up" problem.
Why This Matters:
For Backesters: Use 100% of available data
For Live Trading: Get signals immediately on any timeframe
For Researchers: Analyze complete datasets without gaps
Bottom Line: Infinite EMA is ready to work the moment you add it to your chart - no waiting, no warm-up, no exceptions!
Unlike traditional EMAs that require a "warm-up period" of 200+ bars before showing accurate values, Infinite EMA starts working immediately from bar #1.
This breakthrough eliminates the common problem where the first portion of your chart shows unreliable EMA data. Whether you're analyzing a newly listed cryptocurrency, working with limited historical data, or backtesting strategies, every single bar provides mathematically accurate EMA values.
No more waiting periods, no more unusable data sections - just instant, reliable trend analysis from the moment you apply the indicator to any chart.
🔄 Update Interval Bars Feature
The Update Interval feature allows you to control how frequently the EMA recalculates, providing flexible noise filtering without changing the core mathematics.
Set to 1 for standard behavior (updates every bar), or increase to 5-10 for smoother signals that update less frequently. Higher intervals reduce market noise and false signals but introduce slightly more lag. This is particularly useful on volatile timeframes where you want the EMA's directional bias without every minor price fluctuation affecting the calculation.
Perfect for swing traders who prefer cleaner, more stable trend lines over hyper-responsive indicators.
Conclusion
The Infinite EMA transforms the traditional EMA from a fixed-period tool into a precision instrument with unlimited flexibility. By understanding the Alpha-Period relationship, traders can create custom EMAs that perfectly match their trading style, timeframe, and market conditions.
The "infinite" nature comes from the ability to set any period imaginable - from ultra-fast 2-bar EMAs to glacially slow 10-million-bar EMAs, all controlled through a single Alpha parameter.
________________________________________
Whether you're a beginner looking for simple trend following or a professional researcher analyzing century-long patterns, Infinite EMA adapts to your needs. The power of infinite periods is now in your hands! 🚀
Go forward to the horizon. When you reach it, a new one will open up.
- J. P. Morgan
インジケーター

40 Ticker Cross-Sectional Z-Scores [BackQuant]40 Ticker Cross-Sectional Z-Scores
BackQuant’s 40 Ticker Cross-Sectional Z-Scores is a powerful portfolio management strategy that analyzes the relative performance of up to 40 different assets, comparing them on a cross-sectional basis to identify the top and bottom performers. This indicator computes Z-scores for each asset based on their log returns and evaluates them relative to the mean and standard deviation over a rolling window. The Z-scores represent how far an asset's return deviates from the average, and these values are used to rank the assets, allowing for dynamic asset allocation based on performance.
By focusing on the strongest-performing assets and avoiding the weakest, this strategy aims to enhance returns while managing risk. Additionally, by adjusting for standard deviations, the system offers a risk-adjusted method of ranking assets, making it suitable for traders who want to dynamically allocate capital based on performance metrics rather than just price movements.
Key Features
1. Cross-Sectional Z-Score Calculation:
The system calculates Z-scores for 40 different assets, evaluating their log returns against the mean and standard deviation over a rolling window. This enables users to assess the relative performance of each asset dynamically, highlighting which assets are performing better or worse compared to their historical norms. The Z-score is a useful statistical tool for identifying outliers in asset performance.
2. Asset Ranking and Allocation:
The system ranks assets based on their Z-scores and allocates capital to the top performers. It identifies the top and bottom assets, and traders can allocate capital to the top-performing assets, ensuring that their portfolio is aligned with the best performers. Conversely, the bottom assets are removed from the portfolio, reducing exposure to underperforming assets.
3. Rolling Window for Mean and Standard Deviation Calculations:
The Z-scores are calculated based on rolling means and standard deviations, making the system adaptive to changing market conditions. This rolling calculation window allows the strategy to adjust to recent performance trends and minimize the impact of outdated data.
4. Mean and Standard Deviation Visualization:
The script provides real-time visualizations of the mean (x̄) and standard deviation (σ) of asset returns, helping traders quickly identify trends and volatility in their portfolio. These visual indicators are useful for understanding the current market environment and making more informed allocation decisions.
5. Top & Bottom Performer Tables:
The system generates tables that display the top and bottom performers, ranked by their Z-scores. Traders can quickly see which assets are outperforming and underperforming. These tables provide clear and actionable insights, helping traders make informed decisions about which assets to include in their portfolio.
6. Customizable Parameters:
The strategy allows traders to customize several key parameters, including:
Rolling Calculation Window: Set the window size for the rolling mean and standard deviation calculations.
Top & Bottom Tickers: Choose how many of the top and bottom assets to display and allocate capital to.
Table Orientation: Select between vertical or horizontal table formats to suit the user’s preference.
7. Forward Test & Out-of-Sample Testing:
The system includes out-of-sample forward tests, ensuring that the strategy is evaluated based on real-time performance, not just historical data. This forward testing approach helps validate the robustness of the strategy in dynamic market conditions.
8. Visual Feedback and Alerts:
The system provides visual feedback on the current asset rankings and allocations, with dynamic labels and plots on the chart. Additionally, users receive alerts when allocations change, keeping them informed of important adjustments.
9. Risk Management via Z-Scores and Std Dev:
The system’s approach to asset selection is based on Z-scores, which normalize performance relative to the historical mean. By incorporating standard deviation, it accounts for the volatility and risk associated with each asset. This allows for more precise risk management and portfolio construction.
10. Note on Mean Reversion Strategy:
If you take the inverse of the signals provided by this indicator, the strategy can be used for mean-reversion rather than trend-following. This would involve buying the underperforming assets and selling the outperforming ones. However, it's important to note that this approach does not work well with highly correlated assets, as the relationship between the assets could result in the same directional movement, undermining the effectiveness of the mean-reversion strategy.
References
www.uts.edu.au
onlinelibrary.wiley.com
www.cmegroup.com
Final Thoughts
The 40 Ticker Cross-Sectional Z-Scores strategy offers a data-driven approach to portfolio management, dynamically allocating capital based on the relative performance of assets. By using Z-scores and standard deviations, this strategy ensures that capital is directed to the strongest performers while avoiding weaker assets, ultimately improving the risk-adjusted returns of the portfolio. Whether you’re focused on trend-following or looking to explore mean-reversion strategies, this flexible system can be tailored to suit your investment goals. インジケーター

Performance Metrics With Bracketed Rebalacing [BackQuant]Performance Metrics With Bracketed Rebalancing
The Performance Metrics With Bracketed Rebalancing script offers a robust method for assessing portfolio performance, integrating advanced portfolio metrics with different rebalancing strategies. With a focus on adaptability, the script allows traders to monitor and adjust portfolio weights, equity, and other key financial metrics dynamically. This script provides a versatile approach for evaluating different trading strategies, considering factors like risk-adjusted returns, volatility, and the impact of portfolio rebalancing.
Please take the time to read the following:
Key Features and Benefits of Portfolio Methods
Bracketed Rebalancing:
Bracketed Rebalancing is an advanced strategy designed to trigger portfolio adjustments when an asset's weight surpasses a predefined threshold. This approach minimizes overexposure to any single asset while maintaining flexibility in response to market changes. The strategy is particularly beneficial for mitigating risks that arise from significant asset weight fluctuations. The following image illustrates how this method reacts when asset weights cross the threshold:
Daily Rebalancing:
Unlike the bracketed method, Daily Rebalancing adjusts portfolio weights every trading day, ensuring consistent asset allocation. This method aims for a more even distribution of portfolio weights, making it a suitable option for traders who prefer less sensitivity to individual asset volatility. Here's an example of Daily Rebalancing in action:
No Rebalancing:
For traders who prefer a passive approach, the "No Rebalancing" option allows the portfolio to remain static, without any adjustments to asset weights. This method may appeal to long-term investors or those who believe in the inherent stability of their selected assets. Here’s how the portfolio looks when no rebalancing is applied:
Portfolio Weights Visualization:
One of the standout features of this script is the visual representation of portfolio weights. With adjustable settings, users can track the current allocation of assets in real-time, making it easier to analyze shifts and trends. The following image shows the real-time weight distribution across three assets:
Rolling Drawdown Plot:
Managing drawdown risk is a critical aspect of portfolio management. The Rolling Drawdown Plot visually tracks the drawdown over time, helping traders monitor the risk exposure and performance relative to the peak equity levels. This feature is essential for assessing the portfolio's resilience during market downturns:
Daily Portfolio Returns:
Tracking daily returns is crucial for evaluating the short-term performance of the portfolio. The script allows users to plot daily portfolio returns to gain insights into daily profit or loss, helping traders stay updated on their portfolio’s progress:
Performance Metrics
Net Profit (%):
This metric represents the total return on investment as a percentage of the initial capital. A positive net profit indicates that the portfolio has gained value over the evaluation period, while a negative value suggests a loss. It's a fundamental indicator of overall portfolio performance.
Maximum Drawdown (Max DD):
Maximum Drawdown measures the largest peak-to-trough decline in portfolio value during a specified period. It quantifies the most significant loss an investor would have experienced if they had invested at the highest point and sold at the lowest point within the timeframe. A smaller Max DD indicates better risk management and less exposure to significant losses.
Annual Mean Returns (% p/y):
This metric calculates the average annual return of the portfolio over the evaluation period. It provides insight into the portfolio's ability to generate returns on an annual basis, aiding in performance comparison with other investment opportunities.
Annual Standard Deviation of Returns (% p/y):
This measure indicates the volatility of the portfolio's returns on an annual basis. A higher standard deviation signifies greater variability in returns, implying higher risk, while a lower value suggests more stable returns.
Variance:
Variance is the square of the standard deviation and provides a measure of the dispersion of returns. It helps in understanding the degree of risk associated with the portfolio's returns.
Sortino Ratio:
The Sortino Ratio is a variation of the Sharpe Ratio that only considers downside risk, focusing on negative volatility. It is calculated as the difference between the portfolio's return and the minimum acceptable return (MAR), divided by the downside deviation. A higher Sortino Ratio indicates better risk-adjusted performance, emphasizing the importance of avoiding negative returns.
Sharpe Ratio:
The Sharpe Ratio measures the portfolio's excess return per unit of total risk, as represented by standard deviation. It is calculated by subtracting the risk-free rate from the portfolio's return and dividing by the standard deviation of the portfolio's excess return. A higher Sharpe Ratio indicates more favorable risk-adjusted returns.
Omega Ratio:
The Omega Ratio evaluates the probability of achieving returns above a certain threshold relative to the probability of experiencing returns below that threshold. It is calculated by dividing the cumulative probability of positive returns by the cumulative probability of negative returns. An Omega Ratio greater than 1 indicates a higher likelihood of achieving favorable returns.
Gain-to-Pain Ratio:
The Gain-to-Pain Ratio measures the return per unit of risk, focusing on the magnitude of gains relative to the severity of losses. It is calculated by dividing the total gains by the total losses experienced during the evaluation period. A higher ratio suggests a more favorable balance between reward and risk.
www.linkedin.com
Compound Annual Growth Rate (CAGR) (% p/y):
CAGR represents the mean annual growth rate of the portfolio over a specified period, assuming the investment has been compounding over that time. It provides a smoothed annual rate of growth, eliminating the effects of volatility and offering a clearer picture of long-term performance.
Portfolio Alpha (% p/y):
Portfolio Alpha measures the portfolio's performance relative to a benchmark index, adjusting for risk. It is calculated using the Capital Asset Pricing Model (CAPM) and represents the excess return of the portfolio over the expected return based on its beta and the benchmark's performance. A positive alpha indicates outperformance, while a negative alpha suggests underperformance.
Portfolio Beta:
Portfolio Beta assesses the portfolio's sensitivity to market movements, indicating its exposure to systematic risk. A beta greater than 1 suggests the portfolio is more volatile than the market, while a beta less than 1 indicates lower volatility. Beta is used to understand the portfolio's potential for gains or losses in relation to market fluctuations.
Skewness of Returns:
Skewness measures the asymmetry of the return distribution. A positive skew indicates a distribution with a long right tail, suggesting more frequent small losses and fewer large gains. A negative skew indicates a long left tail, implying more frequent small gains and fewer large losses. Understanding skewness helps in assessing the likelihood of extreme outcomes.
Value at Risk (VaR) 95th Percentile:
VaR at the 95th percentile estimates the maximum potential loss over a specified period, given a 95% confidence level. It provides a threshold value such that there is a 95% probability that the portfolio will not experience a loss greater than this amount.
Conditional Value at Risk (CVaR):
CVaR, also known as Expected Shortfall, measures the average loss exceeding the VaR threshold. It provides insight into the tail risk of the portfolio, indicating the expected loss in the worst-case scenarios beyond the VaR level.
These metrics collectively offer a comprehensive view of the portfolio's performance, risk exposure, and efficiency. By analyzing these indicators, investors can make informed decisions, balancing potential returns with acceptable levels of risk.
Conclusion
The Performance Metrics With Bracketed Rebalancing script provides a comprehensive framework for evaluating and optimizing portfolio performance. By integrating advanced metrics, adaptive rebalancing strategies, and visual analytics, it empowers traders to make informed decisions in managing their investment portfolios. However, it's crucial to consider the implications of rebalancing strategies, as academic research indicates that predictable rebalancing can lead to market impact costs. Therefore, adopting flexible and less predictable rebalancing approaches may enhance portfolio performance and reduce associated costs. インジケーター

CAPM Alpha & BetaThe CAPM Alpha & Beta indicator is a crucial tool in finance and investment analysis derived from the Capital Asset Pricing Model (CAPM) . It provides insights into an asset's risk-adjusted performance (Alpha) and its relationship to broader market movements (Beta). Here’s a breakdown:
1. How Does It Work?
Alpha:
Definition: Alpha measures the portion of an investment's return that is not explained by market movements, i.e., the excess return over and above what the market is expected to deliver.
Purpose: It represents the value a fund manager or strategy adds (or subtracts) from an investment’s performance, adjusting for market risk.
Calculation:
Alpha is derived from comparing actual returns to expected returns predicted by CAPM:
Alpha = Actual Return − (Risk-Free Rate + β × (Market Return − Risk-Free Rate))
Alpha = Actual Return − (Risk-Free Rate + β × (Market Return − Risk-Free Rate))
Interpretation:
Positive Alpha: The investment outperformed its CAPM prediction (good performance for additional value/risk).
Negative Alpha: The investment underperformed its CAPM prediction.
Beta:
Definition: Beta measures the sensitivity of an asset's returns relative to the overall market's returns. It quantifies systematic risk.
Purpose: Indicates how volatile or correlated an investment is relative to the market benchmark (e.g., S&P 500).
Calculation:
Beta is computed as the ratio of the covariance of the asset and market returns to the variance of the market returns:
β = Covariance (Asset Return, Market Return) / Variance (Market Return)
β = Variance (Market Return) Covariance (Asset Return, Market Return)
Interpretation:
Beta = 1: The asset’s price moves in line with the market.
Beta > 1: The asset is more volatile than the market (higher risk/higher potential reward).
Beta < 1: The asset is less volatile than the market (lower risk/lower reward).
Beta < 0: The asset moves inversely to the market.
2. How to Use It?
Using Alpha:
Portfolio Evaluation: Investors use Alpha to gauge whether a portfolio manager or a strategy has successfully outperformed the market on a risk-adjusted basis.
If Alpha is consistently positive, the portfolio may deliver higher-than-expected returns for the given level of risk.
Stock/Asset Selection: Compare Alpha across multiple securities. Positive Alpha signals that the asset may be a good addition to your portfolio for excess returns.
Adjusting Investment Strategy: If Alpha is negative, reassess the asset's role in the portfolio and refine strategies.
Using Beta:
Risk Management:
A high Beta (e.g., 1.5) indicates higher sensitivity to market movements. Use such assets if you want to take on more risk during bullish market phases or expect higher returns.
A low Beta (e.g., 0.7) indicates stability and is useful in diversifying risk in volatile or bearish markets.
Portfolio Diversification: Combine assets with varying Betas to achieve the desired level of market responsiveness and smooth out portfolio volatility.
Monitoring Systematic Risk: Beta helps identify whether an investment aligns with your risk tolerance. For example, high-Beta stocks may not be suitable for conservative investors.
Practical Application:
Use both Alpha and Beta together:
Assess performance with Alpha (excess returns).
Assess risk exposure with Beta (market sensitivity).
Example: A stock with a Beta of 1.2 and a highly positive Alpha might suggest a solid performer that is slightly more volatile than the market, making it a suitable pick for risk-tolerant, return-maximizing investors.
In conclusion, the CAPM Alpha & Beta indicator gives a comprehensive view of an asset's performance and risk. Alpha enables performance evaluation on a risk-adjusted basis, while Beta reveals the level of market risk. Together, they help investors make informed decisions, build optimal portfolios, and align investments with their risk-return preferences. インジケーター

Relative Performance SuiteOverview
The Relative Performance Suite (RPS) is a versatile and comprehensive indicator designed to evaluate an asset's performance relative to a benchmark. By offering multiple methods to measure performance, including Relative Performance, Alpha, and Price Ratio, this tool helps traders and investors assess asset strength, resilience, and overall behavior in different market conditions.
Key Features:
✅ Multiple Performance Measures:
Choose from various relative performance calculations, including:
Relative Performance:
Measures how much an asset has outperformed or underperformed its benchmark over a given period.
Relative Performance (Proportional):
A proportional version of relative performance,
factoring in scaling effects.
Relative Performance (MA Based):
Uses moving averages to smooth performance fluctuations.
Alpha:
A measure of an asset’s performance relative to what would be expected based on its beta and the benchmark’s return. It represents the excess return above the risk-free rate after adjusting for market risk.
Price Ratio:
Compares asset prices directly to determine relative value over time.
✅ Customizable Moving Averages:
Apply different moving average types (SMA, EMA, SMMA, WMA, VWMA) to smooth price inputs and refine calculations.
✅ Beta Calculation:
Includes a Beta measure used in Alpha calculation, which users can toggle the visibility of helping users understand an asset's sensitivity to market movements.
✅ Risk-Free Rate Adjustment:
Incorporate risk-free rates (e.g., US Treasury yields, Fed Funds Rate) for a more accurate calculation of Alpha.
✅ Logarithmic Returns Option:
Users can switch between standard returns and log returns for more refined performance analysis.
✅ Dynamic Color Coding:
Identify outperformance or underperformance with intuitive color coding.
Option to color bars based on relative strength, making chart analysis easier.
✅ Customizable Tables for Data Display:
Overview table summarizing key metrics.
Explanation table offering insights into how values are derived.
How to Use:
Select a Benchmark: Choose a comparison symbol (e.g., TOTAL or SPX ).
Pick a Performance Metric: Use different modes to analyze relative performance.
Customize Calculation Methods: Adjust moving averages, timeframes, and log returns based on preference.
Interpret the Colors & Tables: Utilize the dynamic coloring and tables to quickly assess market conditions.
Ideal For:
Traders looking to compare individual asset performance against an index or benchmark.
Investors analyzing Alpha & Beta to understand risk-adjusted returns.
Market analysts who want a visually intuitive and data-rich performance tracking tool.
This indicator provides a powerful and flexible way to track relative asset strength, helping users make more informed trading decisions.
インジケーター

インジケーター

インジケーター

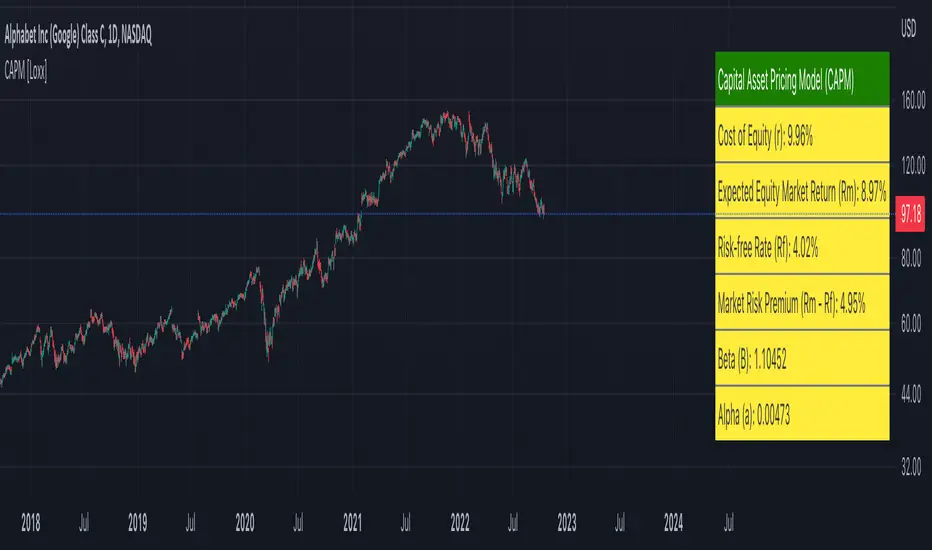
Capital Asset Pricing Model (CAPM) [Loxx]Capital Asset Pricing Model (CAPM) demonstrates how to calculate the Cost of Equity for an underlying asset using Pine Script. This script will only work on the monthly timeframe. While you can change the default inputs, you should study what CAPM is and how this works before doing so. This indicator pulls various types of data from SPY from various timeframes to calculate risk-free rates, market premiums, and log returns. Alpha and Beta are computed using the regression between underlying asset and SPY. This indicator only calculates on the most recent data. If you wish to change this, you'll have to save the script and make adjustments. A few examples where CAPM is used:
Used as the mu factor Geometric Brownian Motion models for options pricing and forecasting price ranges and decay
Calculating the Weighted Average Cost of Capital
Asset pricing
Efficient frontier
Risk and diversification
Security market line
Discounted Cashflow Analysis
Investment bankers use CAPM to value deals
Account firms use CAPM to verify asset prices and assumptions
Real estate firms use variations of CAPM to value properties
... and more
Details of the calculations used here
Rm is calculated using yearly simple returns data from SPY, typically this is just hard coded as 10%.
Rf is pulled from US 10 year bond yields
Beta and Alpha are pulled form monthly returns data of the asset and SPY
In the past, typically this data is purchased from investments banks whose research arms produce values for beta, alpha, risk free rate, and risk premiums. In 2022 ,you can find free estimates for each parameter but these values might not reflect the most current data or research.
History
The CAPM was introduced by Jack Treynor (1961, 1962), William F. Sharpe (1964), John Lintner (1965) and Jan Mossin (1966) independently, building on the earlier work of Harry Markowitz on diversification and modern portfolio theory. Sharpe, Markowitz and Merton Miller jointly received the 1990 Nobel Memorial Prize in Economics for this contribution to the field of financial economics. Fischer Black (1972) developed another version of CAPM, called Black CAPM or zero-beta CAPM, that does not assume the existence of a riskless asset. This version was more robust against empirical testing and was influential in the widespread adoption of the CAPM.
Usage
The CAPM is used to calculate the amount of return that investors need to realize to compensate for a particular level of risk. It subtracts the risk-free rate from the expected rate and weighs it with a factor – beta – to get the risk premium. It then adds the risk premium to the risk-free rate of return to get the rate of return an investor expects as compensation for the risk. The CAPM formula is expressed as follows:
r = Rf + beta (Rm – Rf) + Alpha
Therefore,
Alpha = R – Rf – beta (Rm-Rf)
Where:
R represents the portfolio return
Rf represents the risk-free rate of return
Beta represents the systematic risk of a portfolio
Rm represents the market return, per a benchmark
For example, assuming that the actual return of the fund is 30, the risk-free rate is 8%, beta is 1.1, and the benchmark index return is 20%, alpha is calculated as:
Alpha = (0.30-0.08) – 1.1 (0.20-0.08) = 0.088 or 8.8%
The result shows that the investment in this example outperformed the benchmark index by 8.8%.
The alpha of a portfolio is the excess return it produces compared to a benchmark index. Investors in mutual funds or ETFs often look for a fund with a high alpha in hopes of getting a superior return on investment (ROI).
The alpha ratio is often used along with the beta coefficient, which is a measure of the volatility of an investment. The two ratios are both used in the Capital Assets Pricing Model (CAPM) to analyze a portfolio of investments and assess its theoretical performance.
To see CAPM in action in terms of calculate WACC, see here for an example: finbox.com
Further reading
en.wikipedia.org インジケーター

ストラテジー

ライブラリ

インジケーター

インジケーター

インジケーター

インジケーター

インジケーター

インジケーター

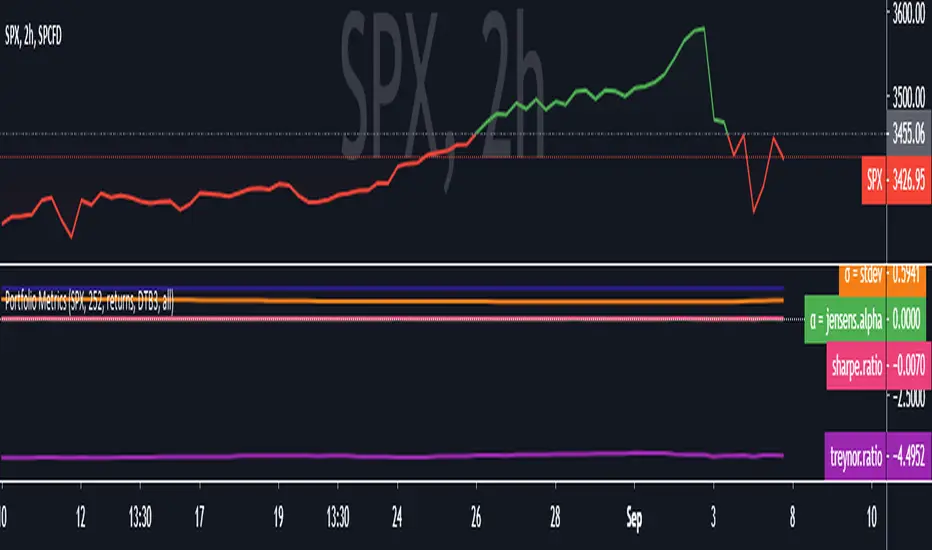
Alpha & BetaAlpha & Beta Indicators for Portfolio Performance
β = Σ Correlation (RP, RM) * (σP/σM)
α P = E(RP) –
Where,
RP = Portfolio Return (or Investment Return)
RM = Market Return (or Benchmark Index)
RF = Risk-Free Rate
How to use the Indicator
RM = SPX (Default)
The Market Return for the indicator has the options of $SPX, $NDX, or $DJI (S&P 500, Nasdaq 100, Dow 30)
RF = FRED: DTB3
The Risk-Free Rate in the Indicator is set to the 3-Month Treasury Bill: Secondary Market Rate
The Default Timeframe is 1260 or 5-Years (252 Trading Days in One Year)
RP = The symbol you enter
HOWEVER , you can determine your portfolio value by following the following directions below.
Note: I am currently working on an indicator that will allow you to insert the weights of your positions.
Complete Portfolio Analysis Directions
You will first need...
a) spreadsheet application - Google Sheets is Free, but Microsoft Excel will convert ticker symbols to Stocks and Retrieve Data.
b) your current stock tickers, quantity of shares, and last price information
In the spreadsheet,
In the first column list the stock tickers...
AMZN
AAPL
TSLA
In the second column list the quantity of shares you own...
5
10
0.20
In the third column insert the last price
Excel: Three tickers will automatically give you the option to "Convert to Stocks",
after conversion, click once on cell and click the small tab in the upper right-hand of the highlighted cell.
Click the tab and a menu pops up
Find "Price", "Price Extended-Hours", or "Previous Close"...
$3,284.72
$497.48
$2,049.98
Next, multiply the number of shares by the price (Stock Market Value)
Excel: in fourth column type "=(B1*C1)", "=(B2*C2)", "=(B3*C3)"...
= $16,423.60
= $4,974.80
= $410.00
add the three calculated numbers together or click "ΣAutoSum" (Portfolio Market Value)
= $21,808.40
Last, divide the market value of AMZN ($16,423.60) by the Portfolio Market Value ($21,808.40) for each of the stocks.
= 0.7531
= 0.2281
= 0.0188
These values are the weight of the stock in your portfolio.
Go back to TradingView
Enter into the "search box" the following...
AMZN*0.7531 + AAPL*0.2281 + TSLA*0.0188
and click Enter
Now you can use the "Alpha & Beta" Indicator to analyze your entire portfolio! インジケーター

インジケーター