GBPJPY 200EMA Pullback [FibonacciFlux]A with-trend 200EMA filter around a counter-trend RSI entry, built for one pair, published with the arithmetic that says confirming it would take about four years, and with the first month of that data saying no.
WHAT IT DOES
On a 1-minute GBPJPY chart:
Long : close above EMA(200) and RSI(14) at or below 30
Short : close below EMA(200) and RSI(14) at or above 70
Hold : 500 bars, then exit. No overlapping positions - while one is open, no new entry is taken.
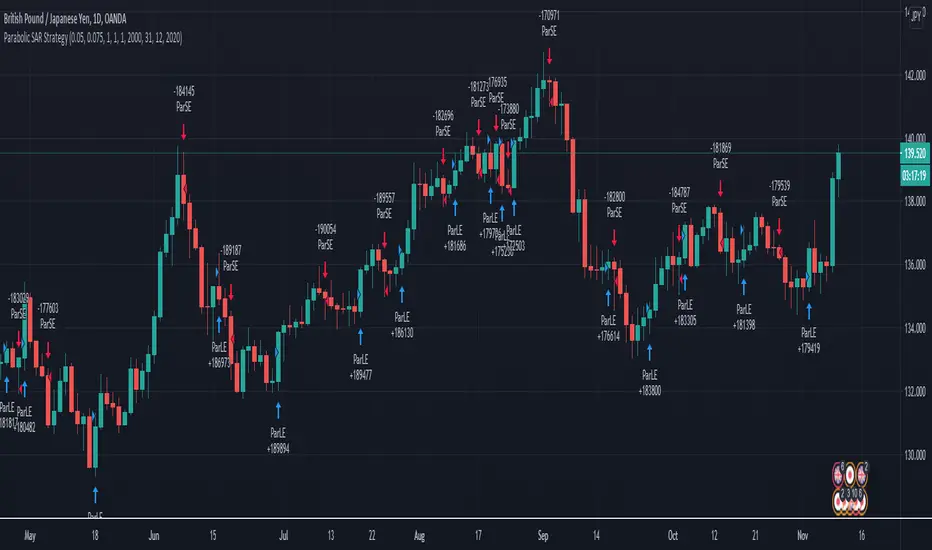
Triangles mark entries, a cross marks the exit, and two Data Window series report the position (+1 / -1 / 0) and the bars remaining, so another script can read them with input.source. That is the whole indicator. It places no orders and computes no equity curve.
WHERE IT CAME FROM
It is the one configuration that survived a holdout in a search run on 2026-07-27, on GBPJPY 1-minute data from histdata, 2002-2026, scored in basis points against the population of all 500-minute moves:
dev 2002-2013 : diff +3.566bp t = +3.56 n = 2,949 MDE 2.805 powered
holdout 2014-2026 : diff +2.186bp t = +2.94 n = 3,179 MDE 2.086 powered
after cost : 1 pip +1.579bp / 2 pip +0.972bp
Selection was made on dev only: of 59 cells, 2 had power, and the larger diff of those 2 was taken. The holdout was scored once.
The pair-specific argument is that on 12 untouched pairs, spanning 17.5 to 20.9 years each, the plain RSI counter-trend leg is positive on every one (+0.122 to +1.600bp) and adding the 200EMA filter drags the average down to +0.097bp - so on those pairs the filter is redundant. GBPJPY is the only one that is negative unfiltered (-0.755bp) and only turns positive once the filter is applied.
NONE OF THAT IS RE-VERIFIED HERE, AND THE ORIGINAL AUTHOR'S OWN RESERVATIONS ARE PART OF THE CLAIM
Those figures come from histdata M1 that is not obtainable from TradingView, so this publication does not reproduce them and does not ask you to take them on faith. They are stated as the provenance of the rule, not as evidence for it. The reservations recorded with the research are reproduced in the source header verbatim in substance, and they are unusually damaging:
The holdout was used twice. The first use was invalid, because the selection rule ranked cells by diff without checking power and picked a cell with n = 109 and no power. As trials, that is a multiplicity of 2.
The time split was chosen after looking at the pooled 24-year aggregate, so it is partially contaminated, and the year-by-year distribution has never been looked at.
The 500-minute hold is a time-based exit. Take-profit and stop-loss were never tested; adding either makes this a different system.
By the research's own account, the only fully uncontaminated evidence is forward data from the research date onward.
SO HERE IS THE FIRST 28 DAYS OF EXACTLY THAT
28,378 one-minute GBPJPY bars from Yahoo Finance, 2026-07-29 to 2026-08-26, entirely after the research date, run through this exact rule:
22 completed round trips
mean +4.118bp, t = +0.46, median -4.17bp, 8 wins of 22
Read no further into that mean than the next paragraph allows, because three of those twenty-two are not what this rule says it does.
THE HOLD IS 500 BARS, NOT 500 MINUTES, AND OVER A WEEKEND THOSE ARE NOT THE SAME THING
The exit fires 500 BARS after entry. On a 1-minute chart that is 500 minutes - except across the weekend close, where the next bar is Monday. In this 28-day window the forward series has four gaps of 49.5 hours, and three positions were opened close enough to Friday's close that their 500-bar hold ran 3,480 minutes of wall clock, or 58 hours, instead of 500 minutes.
Those three trades are the entire positive result. They returned +160.2bp, -12.4bp and -9.5bp, contributing +138.4bp of the +90.6bp total. On the nineteen trades that really are 500-minute holds:
mean -2.514bp, t = -0.44, median -3.96bp, 7 wins of 19
Negative. So the sentence that would have been written here - "the sign agrees with the research" - is false on the trades the rule actually describes. It agrees only if three weekend-spanning holds are counted as if they were 500-minute ones, and one of those is a +160bp outlier.
This is a property of the script and not only of my data. The hold is implemented as a bar counter, so anyone running it live will get 58-hour holds across weekends too, with no marker or setting to tell them apart. It is worth knowing before the exit cross is read as a 500-minute result.
Against a null that circularly shifts the forward-return series while keeping the entry times where they are, over 2,000 draws, the all-22 mean sits at upper-tail p = 0.261 - unremarkable. The two statistics that come closest to significance both point against the rule: the win rate of 36.4% against a null median of 50.0% at lower-tail p = 0.114, and the median trade of -4.17bp against a null median of +0.50bp at lower-tail p = 0.079.
One thing does line up. The rule fires 0.786 times a day here, against 0.725 in the research's holdout and 0.673 in its dev period - so the event definition being tested is the same one, which is the least this check could establish and it did establish it.
One more sizing note. The 22 trades occupy 11,000 of the 28,378 bars, and the 105 raw signals are only 46 contiguous episodes averaging 2.3 bars each. The count of independent observations here is 22 - not 105, and certainly not 28,378.
Two numbers in this write-up are worth labelling before they get quoted back as evidence. The entry count of 22, and the 79% of raw signals the no-overlap gate suppresses, are both EXACTLY invariant when the forward returns are circularly shifted - p = 1.000 and p = 0.926. They describe how often the rule fires and how clustered its signals are, which is a property of the rule and of the autocorrelation of price. Neither can ever be evidence that it predicts anything. They are here for sizing expectations, and for nothing else.
THE NUMBER THAT MATTERS MOST
On the nineteen clean trades, with a 24.9bp spread, the smallest effect this window could resolve at 80% power is 16bp. That is seven times the effect being claimed. (Counting all twenty-two, the spread is 41.9bp and the floor is 25bp, eleven times.)
Detecting +2.186bp at 80% power needs roughly 1,000 trades. At 0.68 clean trades a day, that is about four years of forward data - and that is the optimistic figure, taken on the tighter of the two spreads.
That is not a criticism of the research; it is the size of the thing being looked for. A 2bp edge over a 500-minute hold is small against 42bp of noise per trade, and no amount of care in the backtest changes how long the clean test takes. Until then the claim is neither confirmed nor refuted, and this indicator is a way to watch it rather than evidence for it.
THE PUBLISHED SETTINGS ARE THE WEAKEST OF THEIR OWN NEIGHBOURHOOD
Running the same shift null on nearby parameter cells, upper-tail p for the mean: 0.282 at the published 30/70 with EMA200 and a 500-bar hold, against 0.020 at RSI 40/60, 0.036 at 25/75, 0.055 at a 100-bar hold, 0.060 at EMA150 and 0.075 at a 250-bar hold. Five of the seven neighbours tried beat the published cell.
That is not an argument for moving the settings, and it should not be read as one. Eight cells were looked at; one below 0.05 is what chance produces. A wider 100-cell sweep scored with a family-wise max-t null clears nothing at all - the best cell reaches t = 2.43 against a null whose own maximum averages 2.18, at p = 0.374. What it is an argument for is distrusting the precision of any single cell, including the one shipped here, which was itself chosen as the best of 59 on dev data.
THE CROSS-PAIR CLAIM DOES NOT SHOW UP IN ONE MONTH EITHER
Over the identical 28-day window, restricted to clean 500-minute holds, the same rule returns -3.45bp on EURJPY (n=14), +12.16bp on USDJPY (n=15), +20.11bp on AUDJPY (n=13), -2.30bp on GBPUSD (n=20) and -1.32bp on EURUSD (n=28), against -2.51bp on GBPJPY (n=19). None is significant, and GBPJPY is fourth of six.
Worse for the pair-specific argument, USDJPY reproduces its exact signature and does it harder. The argument is that GBPJPY alone is negative on the raw RSI leg and only turns positive once the EMA filter is applied. On this window USDJPY goes from -3.89bp unfiltered to +8.66bp filtered, a swing of +12.54bp, against GBPJPY's -7.13bp to +4.12bp, a swing of +11.25bp. Neither swing is resolvable - Welch gives p = 0.304 and p = 0.430, and all six pairs' intervals straddle zero - but the thing the argument is named after shows up on a second pair, larger.
The more specific version of the claim fares slightly better. Stripping the EMA200 filter and taking the RSI leg alone, GBPJPY is the most negative of the six at -7.13bp over 50 trades - which is the direction the research predicts - but USDJPY at -3.89bp and EURUSD at -3.64bp are negative too, so "GBPJPY is the only negative one" is not what this month shows. At about 50 trades per pair and a 40bp spread, the standard error is around 6bp, so none of this column separates from zero.
THE FILTER ITSELF DOES NOT CLEAR ON FORWARD DATA, AND THE NULL DECIDES IT
The EMA200 filter is the whole argument for this being a GBPJPY rule. Isolating it - shifting only the close-above-EMA200 condition, which preserves that state's very high persistence - it reaches p = 0.094 and does not clear. Against a null that instead selects bars by an independent coin flip it reaches p = 0.025 and appears to clear. The difference is entirely the null: a per-bar coin flip destroys the clustering that makes the filter's state meaningful, so it is the easier and the wrong comparison. On this month of data the filter is not established.
The filter also behaves like a switch rather than a knob. Between EMA lengths of 9 and 70 it emits zero entries at all, because over that band a close above a fast EMA and RSI at or below 30 almost never coincide. That dead zone reproduces identically on EURJPY, USDJPY and AUDJPY, so it is pair-independent mechanics rather than anything about GBPJPY - which is worth knowing, because the pair-specific story is the reason the filter is there.
WHAT CHANGED IN THIS VERSION
The exit marker was drawn with location.absolute against a boolean, which plots it at price 0. On any instrument that does not trade near zero that both hides the marker and drags the price axis down to zero: loaded on BTCUSDT it compressed every candle into a hairline at the top of the pane and filled the bottom with a grey smear. It now takes the close, so the cross appears where the exit actually happens. It was also a size.tiny grey cross sitting exactly on the close, which is close to invisible against a candle; it is now small and silver. This is the one change that alters what you see.
The entire file was in Japanese - header, input labels, plot titles and alert names - and is now in English. The title was "GBPJPY Pullback", which named a pair and a concept but not a mechanism; it now names the mechanism too. An MPL header was added.
The source noted that it had never been compiled, because it was written without a Pine environment. It compiles.
The measurements above are now in the header and in three input tooltips. No computation changed.
HOW THE NUMBERS WERE CHECKED
The logic was reimplemented outside Pine and cross-checked against this chart's Data Window on BINANCE:BTCUSDT 1-minute - not GBPJPY, deliberately, because Binance klines can be fetched bit-identical to what TradingView charts while a forex feed cannot. Eleven quantities on ten bars: the EMA, the RSI, both raw conditions, both entry flags, the exit flag, the position and the bars remaining. All 110 values round to the decimals TradingView prints, worst raw difference 4.6e-3. The state machine matched exactly on every bar, including one carrying an exit and one where a raw signal was correctly suppressed because a position was already open - so the no-overlap gate and the exit path were exercised rather than assumed.
That gate is not decoration. Over the forward window it suppresses 83 of 105 raw signals, 79% of them. The research notes that a run without it collapsed an apparent n of 1.35 million to an effective 2 and produced a fake t of +66.84.
WHAT THE MEASUREMENTS COVER
The forward test is 28 days, one pair, one data vendor, in a window where GBPJPY fell 81bp. The cross-pair table is the same 28 days. The implementation check is on a crypto pair on a different exchange. Nothing here covers the 2002-2026 research period, transaction costs beyond the figures quoted from the research, or any exit other than the 500-bar timer.
WHAT YOU NEED ON THE CHART BEFORE ANY OF THIS APPEARS
Nothing is discarded manually; Pine's na-propagation does it, so the first entry cannot occur before bar 200. Two consequences on a short chart. The EMA200 seed stays visible well past its first plotted value - recomputing from a start 6,000 bars later, the series disagrees with the settled one for another 432 bars. And with a 500-bar hold, a position opened in the last 500 bars can never show its exit cross. On a 1,500-bar chart that is 13% lost to the seed and 33% to the unclosable tail, leaving about half the chart able to host a complete round trip.
REPAINTING
None by construction. Every value is a confirmed same-bar value and there is no request.security anywhere, so there is no higher-timeframe path by which a value could change after its bar closed. On the still-forming bar the entry flag can appear and disappear as price moves, which is ordinary intrabar behaviour and settles when the bar closes.
Open source under MPL 2.0. Nothing here is a forecast, a signal service, or a claim of profitability.
インジケーター